


 closure

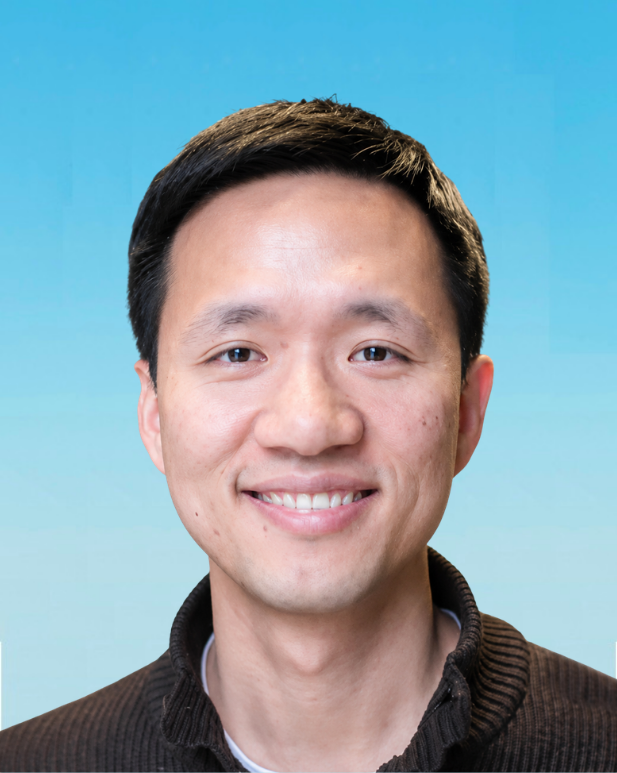
Hui Chen
Fellow
HKUST Institute for Financial Research
Professor of Finance
MIT Sloan School of Management
Hui Chen is the Nomura Professor of Finance and a Professor of Finance at the MIT Sloan School of Management.
His research focuses on asset pricing and its connections with corporate finance. Chen is particularly interested in the interactions between the macro economy and term structure, credit risk, and corporate financing or investment decisions. His recent research projects include application of business cycle models to explain corporate financing behavior and corporate bond pricing, as well as analysis of the effects of incomplete markets on entrepreneurial financing and investments.“Cutting Edge Academic,” a Top 40 Under 40 Business School Professor in 2017 by Poets & Quants, and a top teacher at Harvard by CNBC.
Current Research Focus: Chen's research focuses on (1) the impact of financial frictions on asset pricing and corporate decisions, and (2) the intersections of economics and machine learning. One of his recent projects studies the interactions between financial distress and price competition. Firms tend to compete on prices more when they are in financial distress. More intense competition can in turn reduce firms' profit margins and push weaker firms further into distress. By studying this feedback loop, the paper generates new insights into how the industry structure and strategic concerns affect price competition and credit risk. In another recent study on how to integrate machine learning tools with economics, he proposes building deep-learning-based surrogates for computation-intensive structural models, which can speed up model evaluation and estimation by orders of magnitude.